FX Daily Report
October 8, 2026
USD/JPY Recovers Above 158.00 After a Decline; U.S. Yields Provide Support, but Buyers Remain Cautious Near 158.50
Market Overview
USD/JPY rebounded to 158.29 today after falling to 157.59 during the Tokyo morning session. A recovery in U.S. long-term yields and the U.S.–Japan interest rate differential have encouraged dollar buying on dips.
The pair came under selling pressure as U.S. yields fell after yesterday’s 10-year Treasury auction, but the decline did not persist. Meanwhile, concerns over official warnings against yen weakness remain in the mid-158.00s, keeping buyers cautious about chasing further gains.
The euro and sterling are trading softly against the dollar in the European session, maintaining the broader dollar-buying bias. However, a further rise in USD/JPY will require both higher U.S. yields and sufficient buying to absorb selling near the highs.
The upcoming focus is on U.S. initial jobless claims, the ECB meeting account, and the U.S. 30-year Treasury auction.
USD/JPY
USD/JPY continues to attract buying on dips, while facing resistance around 158.50.
The U.S. 10-year Treasury yield fell from the 5.36% range to the 5.26% range after yesterday’s auction, but recovered to the 5.32% range today, supporting USD/JPY’s rebound.
The immediate focus is whether the pair can break above today’s rebound high of 158.29 and retest the area around 158.50. A decisive break followed by sustained trading above that level could bring a move toward 159.00 into focus.
Conversely, repeated rejection near 158.50 could weaken buying momentum and lead to another test below 158.00. If the pair declines, watch whether buyers return around the Tokyo low of 157.59.
Concerns over official warnings against yen weakness can cap the upside, but do not necessarily imply a sustained decline. Also monitor whether U.S. yields remain elevated and whether new developments encourage yen buying.
U.S. Monetary Policy and Governor Waller’s Remarks
The September FOMC minutes showed that many participants were concerned about upside inflation risks and judged that further rate increases would likely be appropriate before year-end. However, the currency market reaction was limited.
Today, Federal Reserve Governor Waller also indicated that he expected further rate hikes if economic data evolved as anticipated. At the same time, he said there was no need to raise rates at consecutive meetings and that the timing could remain flexible.
The prospect of further hikes should be assessed separately from the urgency of implementing them. Even if the commitment to additional tightening remains intact, dollar buying may be limited unless expectations for a hike at the next meeting strengthen.
The key is whether upcoming U.S. data change views on the timing of further hikes, as well as their necessity.
U.S. Initial Jobless Claims
U.S. initial jobless claims are scheduled for release at 9:30 p.m. JST.
Market expectations are as follows.
Initial jobless claims: 200,000, versus 197,000 previously.
Continuing claims: 1.695 million, versus 1.701 million previously.
Initial claims are expected to rise slightly, while continuing claims are forecast to decline. No major deterioration in employment is anticipated, so a result close to expectations may have a limited currency market impact.
If initial claims come in below expectations and continuing claims also decline, labor market resilience could support U.S. yields and the dollar.
Conversely, if both exceed forecasts, concerns about slowing employment could intensify alongside last week’s weak U.S. employment report, potentially triggering a correction in USD/JPY.
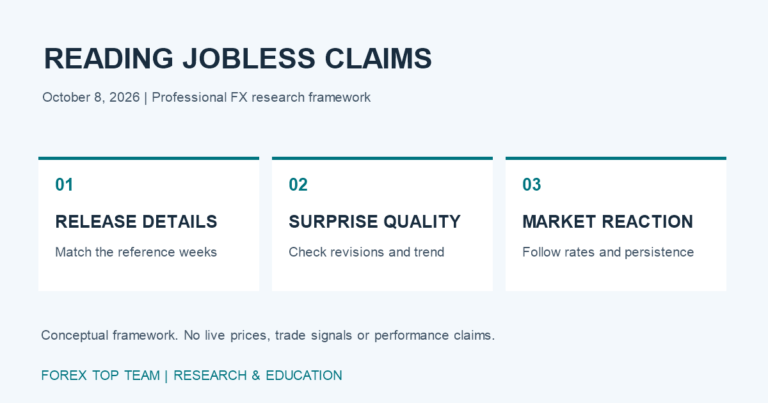
Assessing the Post-Release Reaction
Jobless claims fluctuate from week to week. Rather than determining the labor market’s direction from a single reading, also examine revisions and continuing claims.
It is also important to see whether U.S. yields follow the initial currency market move. Even if strong data lift USD/JPY, a failure of yields to rise and a stall near 158.50 could leave the pair vulnerable to a reversal once the initial buying runs its course.
Even after weak data, stabilization in the 157.00s alongside recovering U.S. yields would suggest that dollar demand remains intact.
Today, assess both the strength of the data and whether USD/JPY can sustain its direction after breaking through key levels.
The Euro and Yen Crosses
After trading around 1.1200, EUR/USD briefly fell to 1.1182. Persistent concerns over France’s fiscal outlook and rising U.S. yields are weighing on the euro’s upside.
The immediate focus is whether EUR/USD can recover above 1.1200 or, on a decline, find support around the previous day’s low of 1.1165.
The account of the September 10 ECB meeting is scheduled for release at 8:30 p.m. JST. Watch whether inflation concerns or caution over the economic outlook dominate. However, even supportive policy signals may produce only a limited euro rebound if concerns over French government bonds intensify.
GBP/USD also briefly fell to 1.3188 before recovering above 1.3200. GBP/JPY returned to the 209.00s during the Tokyo session before falling into the 208.50s.
Resilience in USD/JPY alone may be insufficient to lift yen crosses. The key is whether selling in European currencies against the dollar subsides.
Other Market Drivers
Final U.S. wholesale inventories and wholesale sales data are scheduled for release at 11:00 p.m. JST. Wholesale inventories are forecast to rise 0.7% month on month.
The main event later in the New York session is the USD 22 billion auction of U.S. 30-year Treasury bonds, scheduled for 2:00 a.m. JST on October 9.
Following yesterday’s 10-year Treasury auction, lower yields pushed USD/JPY down. Today, strong demand could again restrain dollar buying through lower yields, while weak demand could push yields higher.
Continue monitoring higher oil prices and equity market weakness. If inflation concerns encourage dollar buying while falling equities prompt yen buying, USD/JPY could become more volatile in both directions.
Key Points for the Overseas Session
Can USD/JPY break above today’s rebound high of 158.29?
Can it break through the area around 158.50 and sustain trading above it?
Will it find support around 157.59 on a decline?
What will initial and continuing U.S. jobless claims show?
Will U.S. yields confirm the initial currency market reaction?
How will markets respond to the ECB meeting account and developments in French government bonds?
Can EUR/USD recover above 1.1200?
How will long-term yields move after the U.S. 30-year Treasury auction?
USD/JPY has reversed its earlier decline as U.S. yields recover. Buying on dips continues, but caution remains around 158.50. A break above that level will require confirmation from U.S. data and the bond market.